Subsidence insurance claims
Subsidence Claim Still Being Monitored? What to Ask Your Insurer
Still being told that more monitoring is needed? Find out what the insurer should explain, which records to request and how to ask for a clear next step.

Why monitoring continues
Seven questions to ask
Getting a clear plan
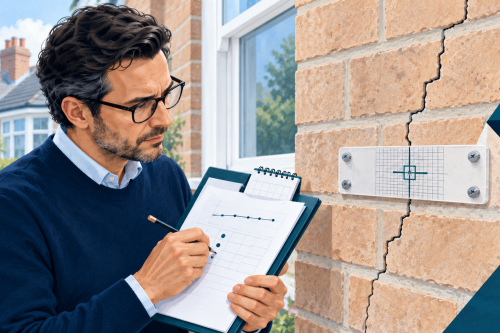
Your insurer has inspected the cracks, arranged monitoring and told you to wait. Months later, the answer is still the same: more readings are needed.
Monitoring can be a necessary part of a subsidence claim. The useful question is what the next period of monitoring is expected to establish, and when someone will review the results. If you cannot get those answers, ask for a written plan.
This guide explains what to request when a subsidence claim appears stuck between investigation and a decision about repairs.
Why does an insurer monitor subsidence?
Monitoring can help establish whether movement continues and whether it changes with the seasons. The Financial Ombudsman Service says monitoring across 12 months can sometimes be reasonable because it covers all seasons. That is a case-specific observation, not a rule requiring every homeowner to wait a year.[1]
The Association of British Insurers also distinguishes between damage where movement has stopped and cases where ongoing movement needs investigation before a lasting solution can be chosen.[2]
The practical implication is that time passing, by itself, does not establish poor claims handling. What matters is how the time is being used.
Is your claim being monitored, or waiting for someone to act?
Start by identifying the decision that is outstanding. Has the insurer accepted that the damage is covered? Is it still deciding the cause? Is it checking whether earlier work has stopped movement? Or have readings been completed but the report remains unreviewed?
Those are different stages. An update saying “monitoring continues” leaves you unable to tell which stage your claim has reached.
Look back through the correspondence for gaps such as:
- appointments that were missed without replacement dates;
- a promised report or technical review that never arrived;
- repeated extensions without an explanation of what remains uncertain;
- completed readings followed by silence;
- changing explanations from different people handling the claim.
These are points to investigate, rather than automatic proof that the insurer is wrong. A dated example gives the insurer something specific to answer.
Under FCA rule ICOBS 8.1.1, insurers must handle claims promptly and fairly and provide appropriate information about their progress. The rule also requires prompt settlement once terms are agreed.[3]
What if monitoring has already lasted 12 months?
Ask the insurer to separate the time needed to gather evidence from any time spent waiting for appointments, reports or decisions. If readings were missed, request an explanation of how that affects the investigation and what will now be done. If readings are complete, ask when the technical review will take place.
A further monitoring period should have a stated purpose. For example, the insurer may be checking the effect of work already carried out. Ask it to explain that purpose in writing and identify the decision the additional evidence will help it make. Reaching the anniversary of your claim does not, by itself, establish that investigation should end.
Seven questions to ask before accepting another extension
Send these to the insurer or the person responsible for the claim and request a written response.
What question are you trying to answer?
Ask whether further monitoring concerns the cause, the extent of movement, seasonal behaviour or the effect of remedial work.
What do the readings already show?
Request the available monitoring results and a plain-language explanation of the current technical conclusion.
Why is more time needed?
Ask what evidence is missing and how the proposed extension is expected to address it.
When are the next readings and review due?
Request dates for both. Collecting a reading and reviewing its significance are separate steps.
Who will make the next decision?
Ask for the responsible team or individual and the decision they are expected to make.
What can progress while monitoring continues?
Ask which outstanding claim tasks depend on the readings and whether other investigations or planning can proceed.
What happens if the position is still unclear?
Ask what the next step will be if the proposed period does not resolve the uncertainty.
The aim is a plan you can follow: a purpose, a date, a responsible person and a next step.
Still getting the same reply? IDS can review the insurer’s explanation alongside your policy and claim correspondence. Request a free claim review.
Wording you can send to your insurer
Adapt this to the facts of your claim:
Subject: Subsidence claim [reference] — request for monitoring plan
I understand that further monitoring may be necessary. Please explain what remains uncertain, what the readings obtained so far show, and why the proposed extension is needed.
Please provide the available monitoring results, the next reading and technical review dates, and the name or team responsible for the next decision. Please also explain which other claim tasks can progress in the meantime.
The update promised on [date] has not been provided. This has affected me by [brief factual explanation]. Please confirm a realistic timetable and how you will keep me informed.
Keep any allegation of delay tied to an actual missed action or unexplained period. Replace the bracketed text and remove anything that does not apply.
Build a short record of the delay
A useful chronology can fit on one page. Record the date the claim was reported, each inspection, the monitoring start date, promised review dates and what actually happened. Add links or references to the relevant emails.
For a claim review, gather your policy wording and schedule, the insurer’s latest explanation, any reports or readings you already hold, and your chronology. Note practical consequences and retain receipts for claimed expenses; being able to show a cost does not automatically make it recoverable.
If damage changes during monitoring, report the change promptly and ask whether the assessment or plan needs updating. Keep dated photographs without disturbing monitoring equipment or starting works that could obscure the evidence.
Can a postcode checker help with a delayed claim?
Our free subsidence area checker gives a broad BGS shrink–swell overview around a postcode. It can help explain the wider ground conditions, but it does not diagnose a property or establish what caused its damage.
An area result cannot demonstrate that monitoring is unnecessary, prove that an insurer should pay or replace evidence from the property. For a delay dispute, focus on the claim’s reports, readings and correspondence.
What if there is still no clear plan?
Make clear to the insurer when you want your concerns treated as a formal complaint. Identify the missed action, the explanation you need and the practical outcome you want — for example, a technical review and a dated plan.
You can also ask IDS to assess whether the available documents support challenging the handling of the claim. For wider issues beyond monitoring, see our guide to challenging an insurance claim that is taking too long.
Eligible consumers can use the Financial Ombudsman Service for free without a paid representative, normally after a final response or eight weeks without one. A referral usually needs to be made within six months of the insurer’s final response; other time limits can also apply. These complaint deadlines are separate from the monitoring timetable.[4]
Get your subsidence claim reviewed
If your claim has stalled during monitoring, send IDS the latest insurer response and the documents you already have. We can review the policy position, the reasons given for waiting and the available evidence, then explain whether we can help with the dispute.
Read more about our support for subsidence and ground-movement insurance disputes. Building inspections and monitoring require an appropriately qualified technical specialist; IDS reviews the insurance dispute and supporting documents.
Request your free claim review
Sources and further reading
Free initial insurance claim review
Still being told to wait?
Send us the insurer’s latest response, your policy and the evidence you already have. We can review the explanation for the delay and whether we can help with the dispute.