

Water damage insurance claims
Water Damage Insurance Claim Rejected or Underpaid? What to Check
Water-damage disputes often turn on the source of the leak, when the damage became visible and the difference between repairing the failed component and repairing the resulting damage.
Separate the cause from the damage
Test gradual-damage reasoning
Evidence the complete repair scope
Water damage is one of the most disruptive home-insurance losses. A small concealed leak can affect ceilings, plaster, flooring, kitchens, electrics and several rooms before the source is discovered. Yet the claim may still be rejected as gradual damage, poor maintenance or wear and tear—or accepted with a settlement that does not fund the necessary reinstatement.
The phrase “water damage” does not decide whether the policy responds. A proper analysis separates the source of the water, the event covered by the policy, the resulting damage, any excluded deterioration and the reasonable cost of putting insured damage right.
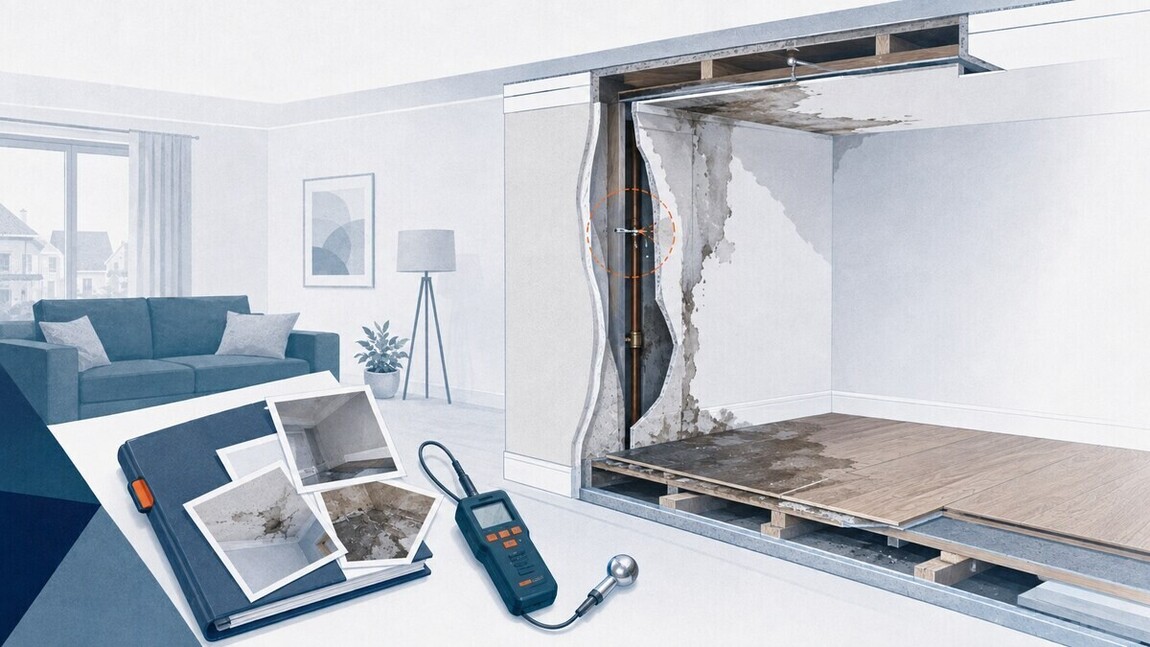
A worn or defective pipe is not necessarily the same thing as the damage caused by escaping water. The failed component, trace and access, drying, resulting damage and reinstatement may each need to be considered separately.
What is an escape-of-water claim?
Home policies commonly cover damage caused by water escaping from fixed pipes, tanks, appliances or heating systems. The precise wording varies, and a policy may treat different parts of the loss differently.
For example, a policy may cover damage to a ceiling, flooring and decoration caused by a leaking pipe but not the cost of replacing the worn pipe itself. It may provide separate “trace and access” cover for locating and reaching the source. It may also exclude damage resulting from a leak that the policyholder knew about and failed to address.
A decision that “the pipe failed because of wear and tear” does not necessarily answer whether the resulting water damage is insured. The policy wording, actual cause and each component of the loss need to be examined.
Why are water damage claims rejected?
Common reasons include:
- the leak developed gradually;
- the policyholder allegedly knew, or should have known, about it earlier;
- the failed seal, grout, pipe or appliance is described as wear and tear;
- the insurer says the water entered from outside and does not meet the relevant definition;
- poor workmanship or faulty installation caused the loss;
- the property was unoccupied beyond a policy limit;
- reasonable steps were not taken to prevent further damage;
- the insurer could not inspect because permanent repairs happened first;
- the damaged item or part of the building falls outside the cover; or
- the insurer alleges non-disclosure or inaccurate information about the property.
Some of these reasons may be valid. Others are too broad unless the insurer can show how the wording applies to the particular damage claimed.
Gradual damage does not end every water claim
Many leaks occur slowly. The central questions may be whether the damage was reasonably discoverable and whether the policyholder acted once signs appeared.
The Financial Ombudsman Service has published a case study involving a concealed leak between a floor and ceiling. The insurer accepted that escape of water caused the damage but relied on a gradual-damage exclusion. The Ombudsman concluded that the policyholder should not reasonably have been aware of the concealed problem and required the insurer to pay the claim.
That case does not mean every hidden leak is covered. It demonstrates why evidence about visibility, timing, access and the policyholder’s response matters. An insurer should not simply equate “happened gradually” with “must have been obvious”.
Separate the different parts of the loss
Review the decision under five distinct headings:
The failed component
The pipe, seal, shower tray, appliance, tank or other item from which the water escaped.
Trace and access
The work required to locate the source and open walls, floors, ceilings or units to reach it.
Resulting damage
Damage to ceilings, walls, floors, fixed units, contents and other insured property.
Drying and mitigation
Emergency work, water extraction, moisture monitoring, decontamination and steps to prevent further loss.
Reinstatement
Repair, replacement, decoration, making good, professional fees and the work needed to return insured property to its pre-loss position.
The insurer may have different reasons and limits for each category. A claim can be partly covered even where the component that failed is excluded. Ask the insurer to identify which items it accepts, which it rejects and the clause relied upon for each.
Evidence that can strengthen a water-damage claim
Useful evidence may include:
- photographs and video taken before emergency work;
- a plumber’s report identifying the source and likely duration;
- the damaged pipe or component, where it can safely be retained;
- meter readings or water-usage information;
- moisture readings, drying logs and a restoration report;
- photographs of concealed areas opened during trace and access;
- maintenance and repair records;
- dates showing when staining, odour, damp or loss of pressure first appeared;
- contractor scopes and reinstatement quotations;
- proof of contents ownership and value; and
- communications showing when the insurer was notified and what it authorised.
A plumber should distinguish observation from assumption. If a report says that a leak was present “for some time”, ask what physical evidence supports that view and whether it establishes that the damage was visible to an ordinary occupier.
Preserve evidence during emergency work
Stopping the leak and preventing further damage may be urgent. Safety comes first, and policies normally expect reasonable mitigation. However, unnecessary disposal or permanent reinstatement before inspection can create an avoidable evidential dispute.
- Notify the insurer promptly.
- Ask what it wants preserved or inspected.
- Photograph every stage of opening-up work.
- Retain failed components where safe and practical.
- Record emergency instructions and attendance times.
- Separate emergency costs from permanent reinstatement.
- Keep damaged contents until disposal is agreed where possible.
If work cannot wait, record why. A flooded electrical system, contaminated water or collapsing ceiling may require immediate action. Take comprehensive photographs and preserve the best available evidence before conditions change.
Has the settlement been calculated properly?
Even after cover is accepted, the repair scope and price can remain disputed. Check whether the insurer’s proposal includes:
- locating and accessing the leak where covered;
- removing wet or contaminated materials;
- professional drying and moisture verification;
- treatment for mould or contamination where necessary;
- reinstating walls, ceilings, floors and fixed units;
- addressing matching adjacent finishes where appropriate;
- moving and storing contents;
- alternative accommodation where the property is uninhabitable and the policy responds;
- professional fees, VAT and compliance work; and
- the period reasonably required to complete the insured repairs.
Compare the insurer’s scope with your contractor’s assessment line by line. A lower total may reflect omitted work rather than cheaper rates.
Where the insurer chooses cash instead of arranging the repair, ask whether the payment is sufficient for the policyholder to obtain the insured work. The position may be different where the insurer offered a fair repair but the policyholder rejected it and insisted on cash.
Watch for an underinsurance reduction
A water-damage claim may trigger a wider review of the declared rebuilding cost or contents value. The insurer may allege that the property was underinsured and apply an average clause, reducing even the part of the loss it accepts.
Ask for:
- the exact average-clause wording;
- the sum insured used;
- the insurer’s asserted correct value and valuation date;
- the report and methodology supporting that value;
- an explanation of how the percentage reduction was calculated; and
- the questions and information used when the policy was arranged or renewed.
Do not confuse market value with rebuilding cost: they measure different things. Read more about underinsurance and average-clause disputes.
How to challenge a rejected or underpaid water claim
Obtain the complete decision
Request the policy clauses, factual findings, reports, photographs and settlement breakdown.
Define each disputed component
Separate the source, trace and access, damage, drying, reinstatement, contents, accommodation and underinsurance issues.
Prepare a chronology
Record when signs first appeared, when the leak was found, notifications, inspections, emergency works and decisions.
Fill genuine evidence gaps
Use an appropriately qualified plumber, surveyor, drying specialist or other expert with a precise question to answer.
Submit a focused complaint
Explain why the wording or evidence does not support the decision and state the reassessment, payment or work required.
Can the Financial Ombudsman review the dispute?
An eligible consumer or smaller business may be able to refer an unresolved insurance complaint to the Financial Ombudsman Service after receiving the insurer’s final response or after eight weeks without one.
The usual referral deadline is six months from the date of a valid final response, although rules and exceptions can affect individual cases. The service is free to use.
The Ombudsman can examine the policy, evidence and fairness of the insurer’s decision. A structured chronology and a clear separation of the disputed components can make the case easier to understand. Read our guidance on preparing a Financial Ombudsman complaint.
When another route may be required
Other claims may require negotiation, mediation or legal proceedings, particularly where the policyholder is outside the Ombudsman’s jurisdiction, the loss is substantial, urgent reinstatement is required or complex expert issues remain unresolved.
Court proceedings involve costs, procedural obligations and limitation risks. Support from a specialist solicitor or barrister may be needed. An Ombudsman complaint should not be assumed to pause a court limitation period.
How Insurance Dispute Service may help
Insurance Dispute Service can review the policy, rejection or settlement decision, plumbing and loss-adjuster evidence, repair scope and chronology before explaining the strongest apparent options.
You can start a free claim review or learn more about our help with escape-of-water and leak disputes.
We cannot guarantee that cover will be accepted or a settlement increased. The outcome depends on the policy wording, cause, evidence and available dispute route.
Your free complaint options
You do not need to use a claims management company to complain to your insurer. You can complain yourself for free. If eligible, you can also refer an unresolved complaint to the Financial Ombudsman Service yourself for free.
Frequently asked questions
Does home insurance cover the leaking pipe itself?
Not always. A policy may cover resulting water damage but exclude repair of a worn or defective component. Trace-and-access cover may deal separately with the cost of finding and reaching the leak.
Can an insurer reject a claim because the leak was gradual?
It may rely on a gradual-damage exclusion, but the wording, cause and whether the damage was reasonably discoverable all matter. Concealed gradual damage is not automatically the same as damage knowingly ignored.
Should I repair a leak before the loss adjuster visits?
Take necessary emergency action to prevent further damage and protect safety, but notify the insurer, photograph the condition and preserve evidence wherever practical.
Can I challenge the insurer’s repair estimate?
Yes. Compare the scope, method, quantities, rates, VAT and omitted work. Support the challenge with a detailed contractor or expert assessment rather than a higher total alone.
Can the Financial Ombudsman review a water-damage rejection?
Potentially, if the complaint and complainant fall within its jurisdiction and relevant time limits. The Ombudsman can examine the policy, evidence and fairness of the insurer’s decision.
Official sources and further reading
- Financial Ombudsman Service: home and buildings insurance complaints
- Financial Ombudsman case study: concealed leak and gradual damage
- Financial Ombudsman Service: settling home insurance claims
This article provides general information, not legal advice. Cover, complaint eligibility and limitation depend on the policy and individual circumstances.
Free initial review
Has Your Water-Damage Claim Been Rejected or Underpaid?
Send us the policy, decision, reports and repair scope. We can examine the disputed reasoning and explain the strongest proportionate options.