Commercial insurance & underinsurance disputes
The Average Clause Has Cut Your Business Insurance Claim — Is the Reduction Correct?
Your insurer has accepted the claim. But instead of paying the loss in full, it says your business was underinsured and has reduced the settlement — potentially by tens or hundreds of thousands of pounds. Before accepting the calculation, there are some important questions worth asking.

1 Average Clause reductions
2 Underinsurance & valuation
3 Commercial claim review
For a business owner, it can be one of the most difficult sentences to read in an insurance claim: “The claim is covered, but you were underinsured.”
The fire happened. The flood happened. The stock was damaged. The machinery needs replacing. The business has suffered the loss.
The insurer may even accept all of that.
But the amount it is prepared to pay can suddenly be dramatically lower because of something called the Average Clause.
In a substantial commercial insurance claim, an underinsurance reduction can be enormous. The important question is not simply whether an Average Clause exists. It is whether the clause, valuation and calculation have been applied correctly to your particular claim.
Allianz currently gives an example involving a company with declared asset values of £9 million when the true values were assessed at £14 million. Following flood damage, the company claimed £4 million for buildings, contents and stock. After average was applied to the underinsured elements, the example payment was £2.95 million.
That illustrates why an underinsurance dispute should not automatically be treated as an accounting technicality.
It can determine whether a business receives enough money to recover.
What is the Average Clause?
The basic principle is relatively straightforward.
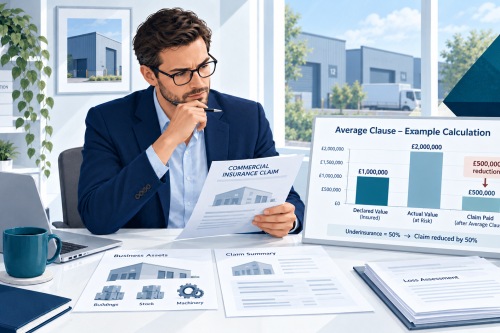
A business insures an asset for a particular amount. The insurer subsequently decides that the amount should have been higher. If the policy contains an applicable Average Clause, the insurer may reduce the claim in proportion to the level of underinsurance.
For example, suppose a building is insured for £600,000. Following a loss, the insurer says its correct reinstatement value was £1 million. The business was therefore insured for 60% of what the insurer says it should have been.
A £300,000 covered loss could potentially be reduced to approximately £180,000, depending upon the precise policy terms.
The painful part for many business owners is that this can affect a partial loss. The building does not necessarily have to be destroyed.
Average is a contractual mechanism used in commercial property insurance and can apply differently depending upon the wording of the particular policy. The FCA has previously noted that commercial policies can contain different thresholds and methods for applying average.
The reduction is only as reliable as the figures and policy wording used to calculate it.
The insurer says you were underinsured. How did it reach that conclusion?
This should be the starting point.
Not:
“How do we convince the insurer not to apply average?”
But:
“How has the insurer established that we were underinsured in the first place?”
If a commercial building was insured for £2 million and the insurer now says it should have been insured for £3 million, that additional £1 million has come from somewhere.
Who calculated the value?
Identify the valuer, loss adjuster, surveyor or other expert whose figure is being relied upon.
What valuation basis was used?
Market value, reinstatement value, declared value and policy-specific definitions are not automatically interchangeable.
What assumptions were made?
Professional fees, demolition, debris removal, VAT, inflation and rebuilding requirements can all affect the number.
Which date matters?
The relevant valuation date and any index-linking mechanism should be checked against the policy.
Does the policy support the reduction?
The insurer's arithmetic still has to be connected to the actual contractual wording.
1. What does the policy actually say?
Never assume that “Average Clause” has exactly the same meaning in every commercial insurance policy.
It does not.
The precise wording matters. Some policies may contain:
- an Average Clause;
- a Special Condition of Average;
- Day One reinstatement provisions;
- percentage tolerances;
- index-linking provisions;
- separate conditions applying to buildings, contents and stock;
- different bases of valuation; or
- specific provisions governing business interruption.
The FCA's historical review of SME claims noted that some commercial policies allowed a degree of underinsurance before average applied — giving an example of a policy where average might only operate if the sum insured fell below 85% of reinstatement costs.
That is an example of policy wording, not a universal rule.
So the first question should be very simple: show us the clause. Then establish precisely what it permits the insurer to do.
2. Has the insurer used the correct reinstatement value?
Commercial property is not necessarily insured by reference to what somebody paid for the building.
Market value and reinstatement value are different things.
A warehouse worth £800,000 on the property market might cost considerably more than £800,000 to demolish, clear and rebuild.
Reinstatement may involve:
- demolition and debris removal;
- construction materials and labour;
- professional fees;
- architects and surveyors;
- planning requirements;
- compliance with current building regulations;
- access difficulties and specialist construction;
- inflation; and
- potentially VAT, depending upon the circumstances and policy.
Allianz specifically highlights materials, labour, professional fees, debris removal and non-recoverable VAT when discussing the appropriate declared value for commercial buildings.
That does not mean every insurer's post-loss valuation is automatically correct.
If a post-loss reinstatement figure is what causes a six-figure reduction in your claim, it is reasonable to ask exactly how that valuation has been constructed.
3. Is the insurer comparing the correct figures?
This sounds obvious. It is not always obvious.
Commercial insurance schedules can refer to:
- Declared Value
- Sum Insured
- Day One Value
- Reinstatement Value
- and various uplift percentages.
These figures are not necessarily interchangeable.
In Allianz's published mid-market example, £6 million of declared building value became a £6.9 million sum insured after a 15% Day One uplift, while the professional valuation at inception was £10 million. Average was then calculated using the applicable policy mechanism.
If the insurer says “you were 40% underinsured”, ask: 40% of what, measured against what?
4. Has the valuation been carried out at the correct point in time?
Imagine a building insured several years ago. Construction costs subsequently increase dramatically. Then the building suffers a fire.
The insurer commissions a valuation after the loss. There may now be a substantial difference between historic figures and present-day reinstatement costs.
That does not automatically tell you which figure the policy requires to be used when deciding whether the property was underinsured.
The relevant valuation date and mechanism will depend upon the policy wording. Index linking may also matter. Allianz explains that insurers commonly use index linking to increase sums insured in response to changing costs and that it is intended to help protect against underinsurance.
So if an insurer is alleging substantial underinsurance, the chronology deserves attention.
When should the relevant value have been measured? What indexation or uplift was applied? Is the insurer's calculation consistent with the policy?
5. Has the insurer applied Average separately to different parts of the claim?
This can be particularly important in a large commercial loss.
A single incident may involve the building, machinery, fixtures and fittings, office equipment, stock, raw materials, finished goods and other contents.
Those elements may not all have been underinsured to the same degree.
Allianz's published example demonstrates precisely this. Following a warehouse flood, the example business suffered losses to buildings, contents and stock. The building element was assessed as 40% underinsured. Contents were assessed as 50% underinsured. But the stock sum insured accurately reflected the replacement cost, so the stock element was paid in full.
One allegation of “underinsurance” does not necessarily mean every part of a commercial claim should receive the same reduction. Ask to see the calculation item by item.
6. What about Business Interruption?
This can be where the numbers become particularly serious.
A business might successfully rebuild its premises and replace its machinery but still suffer a substantial financial loss because it cannot trade normally for months.
Business interruption cover can involve disputes concerning:
- gross profit;
- turnover;
- trends and circumstances;
- increased cost of working;
- savings;
- indemnity periods; and
- the amount that should originally have been insured.
Average can arise here too.
In one published Financial Ombudsman decision concerning a commercial policy, the relevant Hiscox wording said that if the annualised amount insured was less than 85% of actual income — or gross profit where applicable — payment would be reduced in proportion to the underinsurance. That was the wording of that particular policy, not a universal 85% rule.
For a business suffering a major interruption, an argument over the insured gross profit can therefore produce a very substantial difference in the final settlement.
7. Is this really an Average Clause issue — or is the insurer alleging something else?
This is a distinction businesses should not overlook.
An insurer may say “we are applying Average”. But it may also raise questions about the information supplied when the policy was taken out or renewed.
Commercial insurance is subject to the Insurance Act 2015 duty of fair presentation.
Where an insurer alleges a qualifying breach of that duty, different legal remedies can potentially arise. The insurer must, among other things, establish that it would have acted differently had a fair presentation been made — for example, that it would not have entered into the policy or would have done so on different terms.
That is not necessarily the same analysis as simply applying a contractual Average Clause.
Average Clause
A contractual reduction based on the policy wording and the alleged degree of underinsurance.
Policy limit
A separate issue concerning the maximum amount payable under the relevant section of cover.
Fair presentation
A different legal issue concerning information provided when the commercial policy was entered into or renewed.
Policy condition
The insurer may also rely upon a specific condition or term that needs to be examined separately.
The Financial Ombudsman has considered this distinction in commercial insurance decisions when examining whether an insurer was entitled to reduce a claim for alleged underinsurance.
So if the insurer has reduced the claim, establish exactly what it is alleging.
The business may genuinely be underinsured — and the insurer's calculation can still be wrong
This is perhaps the most important point in this article.
Challenging an Average Clause reduction does not necessarily require pretending that the original sum insured was perfect.
Suppose the insurer says a building should have been insured for £5 million. Your own specialist evidence suggests the proper figure was £4.2 million.
The business may still have been underinsured.
But the amount of underinsurance — and therefore potentially the reduction applied to the claim — may be materially different.
The argument is not always “we weren't underinsured”. It may be: “your assessment of the underinsurance is wrong”.
Has Average removed a substantial amount from your claim?
If the reduction is commercially significant, send us the insurer's calculation, policy wording, schedule and valuation evidence. Insurance Dispute Service can carry out a free initial claim review and look at whether the insurer's position appears to be supported by the wording and evidence.
Who originally set the sum insured?
There is another question worth asking: how was the figure on the policy obtained?
Was it:
- supplied directly by the business owner;
- carried forward automatically from a previous year's policy;
- calculated using an insurer's system;
- based upon a broker's recommendation;
- taken from an old valuation;
- based upon the purchase price of the property;
- professionally assessed; or
- index linked over a number of years?
The answer will not automatically determine whether the insurer can apply Average. But it can reveal why the problem arose and whether there are other issues that need investigation.
A six-figure underinsurance problem rarely deserves a one-line explanation.
A £1 million shortfall deserves more than a percentage calculation
Take the Allianz example again. The claim was £4 million. The eventual payment in the example was £2.95 million.
£1.05 million disappeared from the potential recovery because of underinsurance and Average.
Imagine receiving that calculation while your business is trying to recover from a flood.
The question is not whether Average Clauses exist. They plainly do.
The question is: has this clause been applied correctly to this claim?
That can require examination of:
- the full policy wording;
- the policy schedule;
- declared values and sums insured;
- Day One uplifts;
- index linking;
- professional valuations;
- reinstatement estimates;
- stock calculations;
- machinery replacement values;
- VAT treatment;
- business interruption calculations;
- gross profit definitions;
- the underwriting history; and
- the insurer's precise reason for reducing the settlement.
Before you accept the reduction, ask for the workings
If your insurer has substantially reduced a commercial insurance claim because of underinsurance, ask for the calculation in full.
You should be able to understand:
- what value the insurer says should have been insured;
- how that figure was calculated;
- which valuation date has been used;
- what policy clause is being relied upon;
- what percentage of underinsurance has been calculated;
- which parts of the claim Average has been applied to;
- whether any tolerance, Day One or index-linking provisions have been taken into account; and
- whether the insurer is also alleging a breach of the Insurance Act 2015.
If the financial consequence is substantial, those are not minor details.
They are potentially the claim.
Your insurer has valued the underinsurance. That does not mean the valuation cannot be examined.
There is a tendency in large insurance claims for numbers to acquire authority simply because they appear in a loss adjuster's spreadsheet.
£4.8 million. 62%. £1.36 million.
Once calculated and placed into a formal report, the figures can begin to look definitive.
But every figure came from somewhere. Every assumption can be identified. Every valuation has a basis. And every contractual reduction ultimately needs to be justified by the wording and evidence relied upon.
If the Average Clause has removed a substantial amount from your commercial insurance settlement, the size of the reduction alone can justify looking closely at how the insurer arrived at it.
Has your business insurance claim been reduced because of underinsurance?
If your insurer has accepted a commercial claim but significantly reduced the payment using an Average Clause, Insurance Dispute Service can initially review the position.
For a meaningful review, we would normally want to see:
- the full policy wording;
- the policy schedule;
- the insurer or loss adjuster's calculation;
- declared values and sums insured;
- any reinstatement-cost valuation;
- the rejection or settlement letter;
- relevant broker correspondence;
- business interruption calculations where applicable; and
- supporting valuations, invoices or expert reports.
We can then look at the issue that really matters:
Is the reduction the insurer has applied actually supported by the policy, the valuation and the evidence?
Important information
Insurance Dispute Service is an optional service. Businesses can pursue their insurer directly and may have other complaint or legal routes depending upon their size, policy and circumstances. Every commercial insurance dispute depends upon its own wording, evidence, value and applicable deadlines. No particular outcome can be guaranteed.
Frequently asked questions
What is an Average Clause in business insurance?
It is a policy mechanism that can reduce a claim where the insured value is lower than the value that should have been insured. The exact calculation and when it applies depend on the wording of the individual policy.
Can an Average Clause reduce a partial loss?
Potentially, yes. Depending on the policy wording, the insurer may apply the underinsurance percentage to a partial loss rather than only where the property has been completely destroyed.
Can I challenge the insurer's underinsurance calculation?
Potentially. The policy wording, valuation basis, relevant date, sums insured, declared values and the evidence used to establish the alleged correct value all need to be considered.
Does Day One wording affect an Average Clause?
It can. Day One wording may distinguish between the declared value and the policy's sum insured after an uplift. The actual wording and method of calculation should be checked rather than assuming the figures are interchangeable.
Can underinsurance affect a business interruption claim?
Yes, depending on the policy. Business interruption policies may contain provisions that reduce payment where the insured amount for income or gross profit is below the level required by the particular wording.
Is underinsurance the same as a breach of fair presentation?
Not necessarily. A contractual Average Clause and an allegation concerning the Insurance Act 2015 duty of fair presentation are distinct issues and may lead to different analyses and remedies.
What documents should I provide for a commercial claim review?
Ideally provide the full policy and schedule, the insurer or loss adjuster's calculation, declared values, relevant valuations, settlement correspondence, broker communications and any business interruption calculations or expert evidence.
Official sources and further reading
- Allianz: Underinsurance — commercial examples and guidance
- Allianz: Mid-market underinsurance example
- Allianz: Why index linking matters
- Financial Conduct Authority: SME claims thematic review TR15/6
- Financial Ombudsman Service: Published commercial insurance decision DRN-4156125
- Insurance Act 2015
This article provides general information, not legal advice. Every commercial insurance claim depends on its individual circumstances, policy wording, evidence, valuation basis and relevant deadlines.
Free initial commercial claim review
Has the Average Clause Cut Your Business Insurance Settlement?
Send us the insurer's calculation, policy, valuation evidence and supporting documents. We can look at what the insurer has relied upon and consider whether the reduction appears to be supported by the policy and evidence.