Subsidence insurance claims
Subsidence Claim Rejected or Not Paid? What to Check Next
If your insurer says the damage is not subsidence, historic, excluded or worth less than you expected, this guide explains the evidence, questions and next steps that matter.

Understand why the claim was rejected
Test the technical evidence
Choose the right route forward
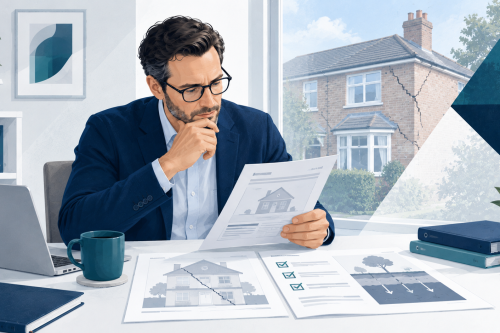
A crack appears above a window. Another runs diagonally through the brickwork. A door that used to close properly begins to catch. You notify the buildings insurer expecting the policy you have paid for year after year to respond — and then the argument begins.
The insurer may say it is not subsidence. It may say the movement started before the policy, the foundations are defective, nearby trees are not responsible, or the damage is simply settlement, thermal movement, poor workmanship or deterioration.
Sometimes the insurer accepts that subsidence has occurred but disputes how much it needs to do about it. For homeowners dealing with subsidence claims that are not paid out, the key issue is not how authoritative the rejection sounds. It is whether the conclusion is actually supported by the policy wording, the physical evidence and the technical investigation.
A rejected subsidence claim is the insurer's conclusion. It does not necessarily mean the conclusion is right. The important question is whether the evidence genuinely supports it.
Has your subsidence claim been rejected?
If you have received a rejection letter, start with the reason being given. Does the insurer say:
- the movement is settlement rather than subsidence;
- the foundations are defective;
- the damage existed before the policy;
- nearby trees are not responsible;
- the property has stopped moving;
- the cracking is cosmetic;
- drainage rather than subsidence caused the damage;
- part of the repair is not insured; or
- underpinning or other stabilisation work is unnecessary?
These are technical or policy conclusions. They can be questioned where the investigation, evidence or policy wording does not properly support them.
Why subsidence claims become so difficult
Periods of prolonged hot and dry weather can cause certain soils, particularly shrinkable clay, to lose moisture and reduce in volume. Trees and large vegetation may add another layer of complexity because their root systems can remove moisture from surrounding ground. Leaking drains and other ground conditions can also be relevant.
But visible cracking does not automatically establish an insured subsidence claim. These cases can involve structural engineers, loss adjusters, drainage specialists, arboriculturalists and geotechnical experts. Monitoring may continue across seasons and different experts may reach different conclusions.
For the homeowner, the difficulty is working out whether the insurer's position is genuinely supported by the evidence or is simply one interpretation of it.
Why are some subsidence claims not paid out?
There are several recurring reasons. Understanding which one applies is important because the challenge should be aimed at the actual reason for rejection.
1. The insurer says it is not subsidence
This is one of the most common disputes. The homeowner sees significant cracking; the insurer's expert attributes the damage to something else.
Possible alternative explanations include settlement, thermal movement, lintel failure, construction defects, inadequate foundations, drainage problems, historic movement or deterioration.
Was movement monitored?
Ask whether crack or level monitoring was undertaken and what the results actually show.
Were foundations examined?
Trial pits can help establish foundation depth, construction and local ground conditions.
Was the ground investigated?
Soil, drainage, roots and seasonal movement may all be relevant to causation.
Was an alternative cause proved?
There is a difference between identifying another cause and simply saying subsidence is unlikely.
Does the report explain its reasoning?
An expert conclusion is more useful when the evidence, methodology and competing explanations are clearly addressed.
The important question is not simply what label has been attached to the cracking. It is: what evidence supports that diagnosis?
2. The insurer says it is settlement
Subsidence and settlement are not necessarily the same thing. Settlement commonly involves a structure compressing the ground beneath it, while subsidence generally involves downward movement of the supporting ground itself. The distinction can matter because policy coverage may be different.
This can become particularly contentious with extensions, conservatories, older properties, homes on clay, buildings with different foundation depths and properties altered over time.
Relevant questions include the age of the structure, when the cracking first appeared, whether movement is continuing or seasonal, what soil lies beneath the building, how deep the foundations are, whether nearby vegetation is relevant and what the monitoring actually shows.
3. The insurer blames the foundations
Another recurring argument is that the building moved because the foundations were inadequate. Sometimes that may be correct. But foundation disputes can be more complicated than they initially appear.
A structure may have remained stable for many years before something changes — unusually dry ground, vegetation growth, leaking drains, altered groundwater, nearby excavation or another external factor.
The central issue may be causation. Did defective construction cause the damage, or did an insured event cause movement that affected an existing structure? Those are different propositions and the evidence should distinguish between them.
4. The insurer says the damage started before the policy
This can arise where cracks existed previously, an earlier survey mentioned movement, the property changed insurer, historic photographs show damage or an earlier owner experienced problems.
But old cracking does not necessarily mean there has been no new insured damage. The important issue can be whether there was further movement during the current period of insurance.
Dated photographs, surveys, monitoring, crack progression, previous policy documents and expert evidence may all be relevant.
5. You changed insurer
Subsidence can develop slowly, creating difficulties where a homeowner changes insurer shortly before the damage becomes obvious. The current insurer may say the problem began before its policy, while the previous insurer may say the claim was not notified to it.
Where the insurers subscribe to the Association of British Insurers' Domestic Subsidence Agreement, established handling arrangements may determine which insurer deals with the claim following a change of insurer. The precise position depends on when the claim was notified and the circumstances of the policy change.
6. Trees are being blamed — or ignored
A tree being close to a property does not automatically prove that it caused the movement. Equally, the fact that a tree has stood there for many years does not, by itself, establish that it cannot be relevant.
A proper assessment may require consideration of tree species, height, distance from the property, root identification, soil type, soil moisture, foundation depth, seasonal movement and monitoring data.
The insurer has accepted subsidence — but is offering too little
Not every problematic subsidence claim is formally rejected. Sometimes the insurer accepts that subsidence has occurred but the dispute moves to the repair or settlement.
The insurer may propose crack repairs, redecoration, limited structural work, vegetation management, drainage repairs or a cash settlement. The homeowner may believe more extensive work is required.
The question is not simply whether the insurer has accepted the claim. The question is whether the proposed works will properly deal with the insured damage and whether the repair strategy is supported by the evidence.
If movement is continuing, repeatedly filling cracks may achieve very little. The cause and stability of the building need to be considered alongside cosmetic reinstatement. Read our separate guide on subsidence repairs where the movement may not have stopped.
What should you do after a subsidence claim is rejected?
1. Get the rejection in writing
You need to understand exactly why the insurer is refusing or restricting the claim.
2. Request the evidence
Ask for the technical material relied upon, which may include:
- structural engineer and loss adjuster reports;
- crack or level-monitoring records;
- drainage investigations and CCTV;
- trial-pit or borehole results;
- soil and root-analysis reports;
- arboricultural reports;
- site photographs; and
- other expert evidence relied upon.
3. Identify the decisive issue
Most complicated claims eventually reduce to one or two important disagreements. Identify them before commissioning unnecessary reports or sending a lengthy complaint.
4. Compare the evidence with the policy
What happened physically and what the policy covers are separate questions. Both matter.
5. Get the position reviewed before accepting it
You do not need to know whether the insurer is definitely wrong before asking for a review. The first task is to identify what the insurer is relying upon, what may be missing and where the genuine point of dispute lies.
The rejection letter is only the starting point
An insurer may express its decision in only a few paragraphs. The investigation behind that decision may involve hundreds of pages of reports, photographs, measurements, monitoring data and correspondence.
A rejection letter tells you what the insurer has decided. It does not necessarily tell you whether the evidence properly supports that decision.
When a disputed subsidence claim is reviewed, the important questions often include: What was investigated? What was not investigated? Which expert reached the conclusion? What evidence did they rely upon? Were competing explanations considered? And does the policy wording actually support the result?
What evidence matters in a disputed subsidence claim?
The strongest evidence varies from case to case, but the following material is commonly important:
Dated photographs
Useful for establishing when cracking appeared and whether it progressed.
Crack or level monitoring
Can help show whether movement continues, its extent and whether it has a seasonal pattern.
Trial pits and ground investigation
Can reveal foundation depth, ground conditions and information relevant to the movement mechanism.
Soil testing and root identification
Potentially important where clay shrinkage and vegetation are suspected.
Drainage CCTV
Useful where leaking or defective drains may have affected the supporting ground.
Previous surveys and engineering reports
These may establish the property's earlier condition and are often central to the technical dispute. But an expert report should do more than announce a conclusion: it should explain how that conclusion was reached.
Can the Financial Ombudsman consider a rejected subsidence claim?
The Financial Ombudsman Service considers complaints involving subsidence and other ground movement where the complainant and policy fall within its jurisdiction. It can look at whether the insurer investigated thoroughly, how it interpreted the evidence and whether the proposed repair or settlement was fair in the circumstances.
Before going to the Ombudsman, you normally need to make a formal complaint to the insurer. If you are eligible, you can generally refer the matter after receiving the insurer's final response or once the applicable complaint-response period has expired.
You can read our guide to preparing a Financial Ombudsman complaint before deciding whether that route is appropriate.
How Insurance Dispute Service may help
Insurance Dispute Service reviews rejected, underpaid, delayed and disputed subsidence claims. We can examine the policy wording, insurer's decision, engineering and loss-adjuster reports, monitoring material and proposed repair or settlement to identify the central issue.
That may involve a dispute about the diagnosis, causation, policy coverage, previous damage, insurer responsibility after a change of provider, the adequacy of the investigation, the repair strategy or the amount being offered.
You can start a free claim review or read more about our specialist support for subsidence and ground-movement insurance disputes.
We cannot guarantee that an insurer will reverse its position. The purpose of the initial review is to identify whether there appears to be a genuine basis for challenge and what proportionate routes may be available.
Your free complaint options
You do not need to use Insurance Dispute Service or another claims management company to complain to your insurer. You can complain directly to your insurer without charge and, where eligible, refer an unresolved complaint to the Financial Ombudsman Service yourself for free.
Frequently asked questions
Can an insurer refuse a subsidence claim?
Yes, if it concludes that the policy does not respond or that the evidence establishes another cause. But the rejection should be tested against the policy wording, the investigation and the technical evidence.
Why has my subsidence insurance claim been rejected?
Common reasons include a finding of settlement or another cause, alleged defective construction, historic damage, insufficient evidence of active subsidence, an exclusion or a dispute about when the movement occurred.
What happens if my insurer says the cracks are settlement?
The technical basis for that diagnosis should be examined. The age of the structure, foundation details, soil conditions, movement pattern and monitoring evidence may all be relevant.
Can I challenge a rejected subsidence claim?
Potentially. The first step is to identify the precise reason for rejection and the evidence relied upon. A challenge should address that point rather than simply repeat that you disagree.
What if my insurer says the foundations are defective?
That may be relevant, but the cause of the actual movement still needs to be established. A pre-existing feature and the cause of a particular episode of damage are not necessarily the same thing.
What if my claim has been accepted but the payout is too low?
The repair scope, cash settlement, professional fees and the evidence supporting the insurer's proposal can be reviewed. Acceptance of liability does not automatically resolve a dispute about the remedy.
Do I need my own structural engineer?
Not in every case. It can be sensible to review the evidence that already exists before commissioning further expert work, particularly where the insurer's own reasoning has not yet been clearly identified.
Can a subsidence claim be affected because I changed insurer?
Yes. Timing and policy periods can become important. Where participating insurers are involved, the ABI Domestic Subsidence Agreement may affect which insurer handles the claim.
Official sources and further reading
- Financial Ombudsman Service: subsidence and other types of ground movement
- Association of British Insurers: Domestic Subsidence Claims Agreement and guidelines
- Financial Conduct Authority: how to complain
This article provides general information, not legal advice. Every insurance claim depends on its individual circumstances, evidence, policy wording, eligibility and relevant deadlines.
Free initial review
Has Your Subsidence Claim Been Rejected or Underpaid?
If you already have the insurer's decision, technical report or settlement proposal, send it to us. We can examine what the insurer is relying upon and identify the central dispute before you decide what to do next.