Financial Ombudsman & insurance complaints
Financial Ombudsman Reveals Its Insurance Uphold Rates
The latest figures show that in several major insurance categories, considerably fewer than half of resolved complaints were upheld in the consumer's favour. Before automatically referring a rejected or underpaid claim to the Ombudsman, it can pay to understand the case you are asking it to decide.

1 Latest FOS uphold rates
2 What the figures actually mean
3 Review the claim before escalation
When an insurer rejects a claim, delays payment or offers substantially less than the policyholder believes the claim is worth, the response is often almost automatic: “Take it to the Financial Ombudsman.”
The Financial Ombudsman Service is free to consumers, independent of the insurer and exists to resolve complaints between financial businesses and their customers. For many disputes, it can be an important route.
But its latest published figures contain an equally important message: referring a complaint to the Ombudsman is not the same thing as having a strong, well-evidenced insurance dispute.
The Ombudsman should not automatically be treated as the first external route simply because an insurer has said no. First understand the policy wording, the insurer's reasoning, the evidence and the value of the claim — then decide which route is strongest.
What the latest Financial Ombudsman figures show
The Financial Ombudsman Service published its Q1 2026/27 complaints data on 22 July 2026, covering complaints received and cases resolved between April and June 2026.
Across all financial products, the Ombudsman said it upheld 26% of cases it resolved in favour of the consumer during the quarter. Excluding motor finance commission cases, the overall uphold rate was 30%.
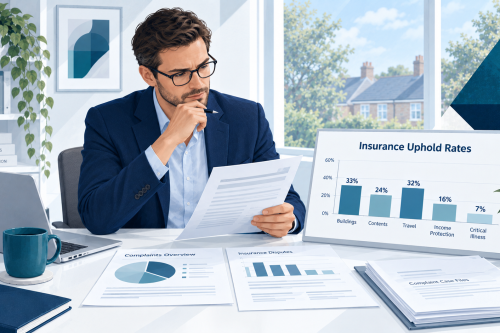
For insurance, the individual product figures are particularly striking:
33%Buildings insurance1,766 new complaints
24%Contents insurance472 new complaints
33%Car or motorcycle insurance4,096 new complaints
32%Travel insurance1,275 new complaints
16%Income protection299 new complaints
7%Critical illness cover175 new complaints
| Insurance product | New complaints | Uphold rate |
|---|---|---|
| Buildings insurance | 1,766 | 33% |
| Commercial property insurance | 402 | 37% |
| Contents insurance | 472 | 24% |
| Home emergency insurance | 550 | 32% |
| Car or motorcycle insurance | 4,096 | 33% |
| Commercial vehicle insurance | 283 | 45% |
| Travel insurance | 1,275 | 32% |
| Pet insurance | 593 | 29% |
| Legal expenses insurance | 299 | 26% |
| Income protection insurance | 299 | 16% |
| Private medical or dental insurance | 532 | 20% |
| Critical illness cover | 175 | 7% |
Source: Financial Ombudsman Service, Quarterly complaints data Q1 2026/27. An uphold rate is not a prediction of the outcome of any individual claim. FOS publishes uphold rates where it has resolved at least 30 complaints about the relevant product or service in the period.
For buildings insurance, the uphold rate was one in three. For contents insurance, fewer than one in four. For income protection, fewer than one in six. Those figures do not tell you whether your claim will succeed — but they do show why preparation matters.
What does an Ombudsman “uphold rate” actually mean?
The Financial Ombudsman describes a complaint as “upheld” where the case is closed with a change in outcome in favour of the complainant.
That definition matters. A 33% uphold rate does not mean every buildings insurance claimant has a 33% chance of winning. Every dispute turns on its own facts, policy wording, evidence, chronology and circumstances.
Nor does a complaint that is not upheld necessarily mean the consumer was unreasonable to complain. The statistics are aggregate figures across many different disputes and should not be treated as individual success probabilities.
What they do demonstrate is much simpler: there is no automatic reversal of an insurer's decision merely because a dispute reaches FOS.
Insurance complaints are still arriving in significant numbers
The same Q1 data recorded 4,096 new car or motorcycle insurance complaints, 1,766 buildings insurance complaints and 1,275 travel insurance complaints.
FOS also reported that car and motorcycle insurance complaints had increased compared with the same quarter a year earlier, with consumers raising concerns including claim values, policy cancellations and claim delays. Travel insurance complaints were also up year on year, with declined claims remaining the most common issue.
These are familiar insurance dispute problems:
- a claim has been rejected;
- an exclusion has been relied upon;
- a loss adjuster or expert has reached a conclusion the policyholder disputes;
- the insurer says damage is wear and tear rather than an insured event;
- a property claim has been substantially undervalued;
- causation is disputed;
- the claim has stalled; or
- months of correspondence have produced little progress.
The natural temptation is to escalate immediately. But escalation and preparation are not the same thing.
The Ombudsman looks at the evidence — so what case are you giving it?
FOS explains that its case handlers consider what the consumer and financial business have said and the paperwork provided. In insurance disputes, relevant material can include the policy wording, expert reports, photographs, claim notes, correspondence, valuations and settlement calculations.
That creates a series of important questions before a complaint is escalated:
What exactly is the insurer relying upon?
Identify the decisive policy term, exclusion, factual conclusion or valuation issue rather than arguing with the decision in general terms.
Is the insurer's evidence complete?
Review the reports, photographs, chronology and assumptions that appear to support the insurer's position.
Is stronger evidence available?
Consider whether an expert report, valuation, repair evidence or other documentation could materially change the analysis.
Has the policy wording been applied correctly?
Check whether the actual wording supports the conclusion the insurer has reached.
What outcome are you asking for?
Be clear whether the dispute concerns liability, valuation, reinstatement, delay, an exclusion, compensation or another specific issue.
Going to the Ombudsman and having a strong case are not the same thing
FOS can ask the parties for further information, but the quality and relevance of the evidence still matter. A complaint is stronger when the disputed issues are clear, the insurer's reasoning has been tested and the supporting material has been organised around the points that actually decide the claim.
Before escalation comes assessment
This is where we believe serious insurance disputes should be approached differently.
The first question should not automatically be:
“How do I take this to the Ombudsman?”
It should first be:
“Why has my claim failed — and does the insurer's position stand up to scrutiny?”
A proper claim review can involve examining the policy wording, endorsements and exclusions; the insurer's rejection or settlement reasoning; expert evidence; photographs and reports; the chronology of the claim; correspondence with loss adjusters and insurers; the calculation of loss; and the evidence required to challenge the insurer's position.
Only after that exercise can a policyholder properly understand the strengths and weaknesses of the dispute.
Sometimes the Ombudsman may indeed be the appropriate route. Sometimes stronger representations should first be made directly to the insurer. Sometimes additional evidence may materially change the position. Sometimes negotiation may be possible. And in appropriate cases, legal action may need to be considered.
The route should follow the evidence. The evidence should not be assembled around a route that has already been chosen.
Free does not mean consequence-free
The Financial Ombudsman Service is free for consumers to use, and consumers do not need to use a representative to make a complaint.
However, FOS explains that if a consumer accepts an ombudsman's final decision within the specified timeframe, that decision becomes legally binding on the financial business. It also says it is unlikely the consumer will then be able to pursue the business through the courts for the same complaint.
FOS itself suggests considering independent legal advice if a consumer is unsure about accepting a settlement or final decision.
That is another reason why the value and strength of a substantial insurance dispute can be worth understanding before the process reaches its final stage.
There is also a deadline
You normally need to complain to the insurer first. For most complaints, the business has up to eight weeks to consider the complaint and issue its final response.
Once the final response has been issued, a consumer will normally have six months from the date of that final response to refer the complaint to the Financial Ombudsman Service. There are exceptions, but a policyholder should not assume that continuing correspondence with the insurer automatically extends the deadline.
Important: do not miss your FOS deadline
Reviewing your options should not mean allowing an applicable time limit to expire. If you have received a final response from your insurer, check the date and the referral deadline stated in the letter.
A rejected insurance claim is not necessarily the end of the claim
Insurer decisions can be challenged. Policy wording can be disputed. Claim valuations can be tested. Expert conclusions can sometimes be challenged by other evidence. And insurers can change their position.
But the starting point should be understanding why the insurer reached its decision and whether that decision is properly supported.
The latest Ombudsman figures underline why that matters.
A 33% buildings insurance uphold rate does not mean your buildings claim has a 33% chance of succeeding. A 32% travel insurance uphold rate does not mean your travel claim has a 32% chance of succeeding. And a 16% income-protection uphold rate does not mean somebody with a well-founded dispute should abandon it.
Statistics cannot decide an individual insurance dispute. But they can show why simply “going to FOS” should not be confused with building the strongest possible case.
Before you go to the Financial Ombudsman, find out what your claim may actually be worth
If your insurance claim has been rejected, underpaid, delayed or disputed, Insurance Dispute Service can review what has happened before you decide on your next move.
Our starting point is not simply to complete another complaint form.
We look at the claim. We look at the insurer's reasoning. We look at the policy. We look at the evidence. And we identify what appears to be the strongest route towards resolving the dispute.
That may involve challenging the insurer directly, developing the evidence, pursuing a complaint, considering the Financial Ombudsman process or, where appropriate, considering legal action.
Do not automatically assume the insurer is right. And do not automatically assume the Financial Ombudsman is your only next step.
What should you send us for a free initial review?
- your policy schedule and full policy wording;
- the insurer's rejection, settlement or final response letter;
- relevant insurer, loss adjuster and claims-handler correspondence;
- expert, surveyor, engineer or medical reports;
- photographs, estimates, valuations and invoices;
- documents showing how any settlement figure was calculated; and
- a short chronology of the claim and dispute.
If you are unsure whether a document matters, include it. It is often easier to assess relevance once the whole dispute is visible.
Frequently asked questions
What was the Financial Ombudsman uphold rate for buildings insurance?
For Q1 2026/27, covering April to June 2026, FOS published a 33% uphold rate for buildings insurance. That figure is an aggregate statistic and is not the probability of success for an individual buildings insurance complaint.
Does a low uphold rate mean I should not use the Financial Ombudsman?
No. FOS can be an appropriate and important route. The point is that a policyholder should understand the evidence, policy wording, insurer's reasoning, deadlines and available routes rather than treating FOS as an automatic next step.
Can I complain to the insurer before using FOS?
Yes — and you normally need to give the financial business the opportunity to investigate the complaint first. For most complaints, the business has up to eight weeks to issue its final response.
How long do I have to refer an insurance complaint to FOS?
Normally you have six months from the date on the financial business's final response. Exceptions can apply, but you should check the deadline stated in your own final response letter.
Does accepting an Ombudsman final decision affect court action?
FOS states that if you accept the ombudsman's final decision within the specified timeframe it becomes binding on the business, and it is unlikely you will then be able to pursue the business through the courts for the same complaint.
Can IDS review my claim before I decide whether to use FOS?
Yes. Insurance Dispute Service can review rejected, underpaid, delayed and disputed insurance claims, including the insurer's reasoning, policy wording and supporting evidence, before you decide on the next route.
Official sources and further reading
- Financial Ombudsman Service: Quarterly complaints data Q1 2026/27
- Financial Ombudsman Service: Q1 2026/27 complaints announcement
- Financial Ombudsman Service: How we resolve complaints and final decisions
- Financial Ombudsman Service: How to complain and time limits
This article provides general information, not legal advice. Financial Ombudsman statistics are aggregate figures and do not predict the outcome of any individual complaint. Every insurance dispute depends on its facts, evidence, policy wording, eligibility and applicable deadlines.
Free initial claim review
Thinking About Going to the Financial Ombudsman?
Before you decide on the next step, send us the insurer's decision, policy and supporting documents. We can review the dispute as a whole and identify what appears to be the strongest route forward.